Independent Valuation Support for Impairment Testing
The Valuation Group provides valuation support for goodwill and intangible asset impairment matters involving reporting units, indefinite-lived intangible assets, triggering events, fair value analysis, and financial reporting review.
Our work supports CFOs, controllers, auditors, CPA firms, attorneys, boards, investors, private companies, and advisory teams that need documented valuation analysis for impairment testing and related reporting matters.

Why The Valuation Group
Goodwill and intangible asset impairment analysis requires more than comparing current performance to prior expectations. The valuation must address the reporting unit, the assets being tested, the economic facts, the valuation date, market conditions, expected cash flow, discount rates, company-specific risk, and the evidence supporting the fair value conclusion.
Our impairment work focuses on the economic evidence behind the reporting unit or intangible asset being tested: performance trends, cash flow expectations, market conditions, remaining useful life, risk, and the assumptions supporting fair value.
We provide valuation support for goodwill impairment matters involving reporting units, business units, acquisitions, changes in financial performance, adverse market conditions, customer loss, margin compression, increased risk, or other triggering events.
Our analysis may address expected cash flow, market multiples, industry trends, company-specific risk, discount rates, revenue expectations, profitability, and the relationship between carrying value and fair value.
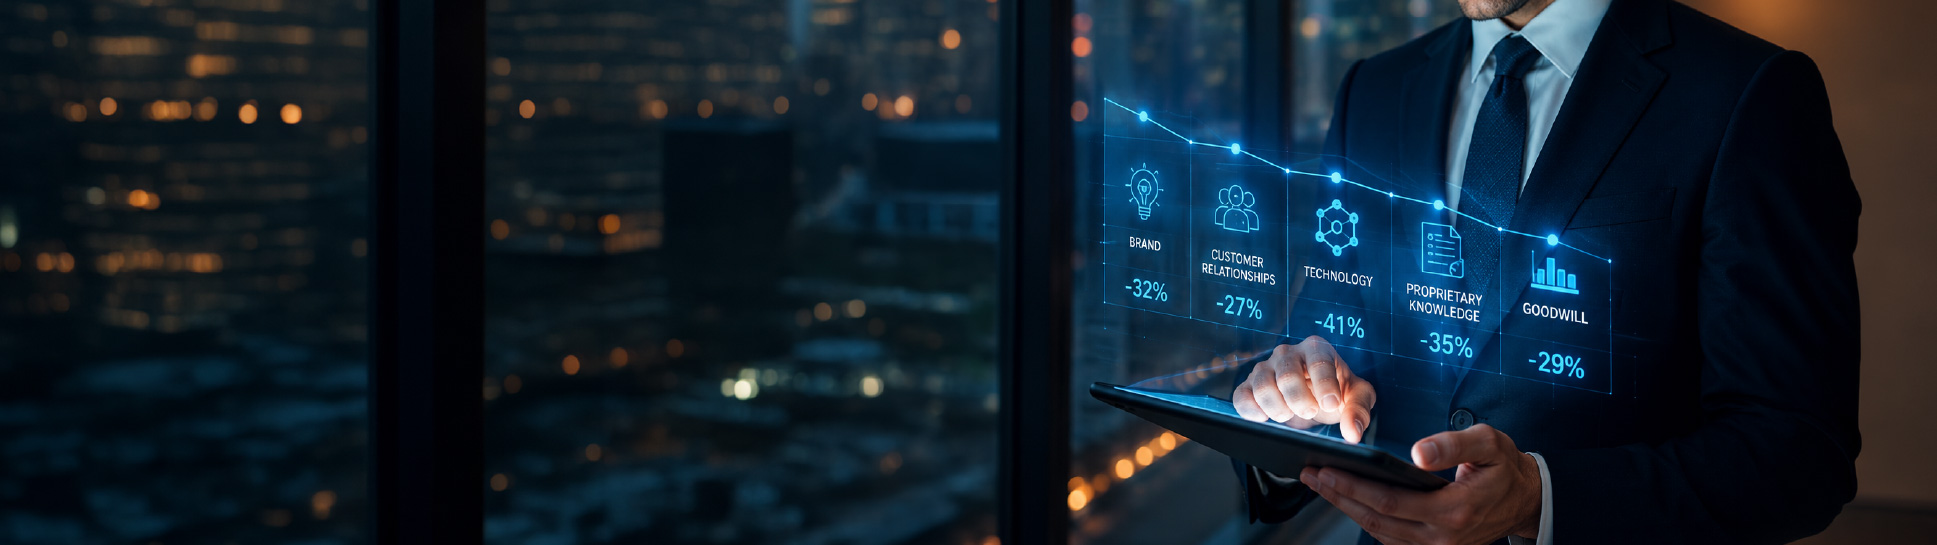
We provide valuation analysis for intangible assets including trade names, trademarks, customer relationships, developed technology, licensing rights, contract rights, non-compete agreements, and other identifiable intangible assets.
Our work considers the expected economic benefit of the asset, remaining useful life, revenue contribution, risk, legal or contractual rights, market position, and the assumptions supporting the impairment analysis.
Impairment testing may be required after changes in business performance, market conditions, financing conditions, customer relationships, product demand, competitive position, regulatory environment, or transaction expectations.
The Valuation Group assists professional teams in evaluating the valuation implications of those events and documenting the financial evidence behind the conclusion.
Goodwill impairment analysis often requires valuation of a reporting unit or business unit. We analyze the relevant business, its financial performance, expected cash flow, risk profile, industry position, and market evidence.
Our work is designed to make the valuation conclusion understandable to management, auditors, CPA firms, boards, and advisory teams.
Related Valuation Issues
ASC 805 Purchase
Price Allocations
Goodwill and identifiable intangible assets often arise from acquisition accounting and may require later impairment analysis.